Market Overview
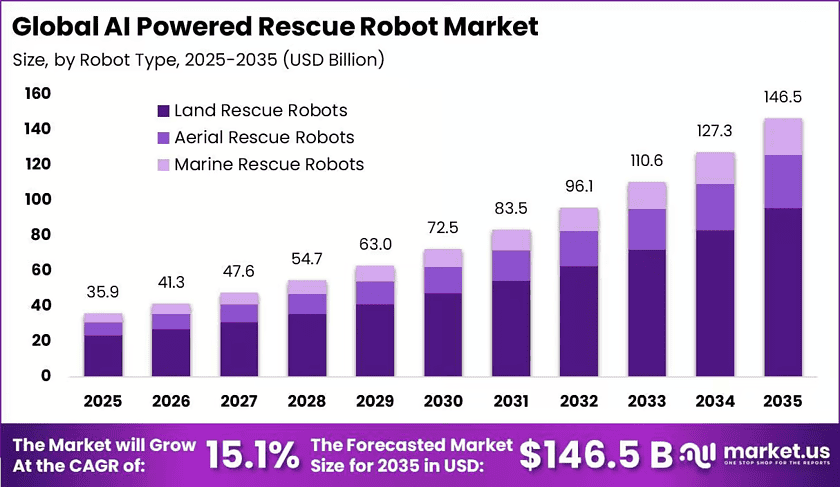
New York, NY – October 21, 2026 – The Global AI-Powered Rescue Robot Market reached USD 35.9 billion in 2025. Analysts project it will hit USD 146.5 billion by 2035, growing at a 15.1% CAGR. North America led the market in 2025 with a 41.2% share and about USD 14.7 billion in revenue. Consequently, this steady rise shows that emergency agencies now treat intelligent rescue machines as core safety tools.
Additionally, natural disasters keep growing in number and cost. According to CRED, 393 disasters in 2024 caused over 16,750 deaths and affected 167.2 million people. These events also created USD 241.95 billion in losses. Consequently, governments seek robots that find victims faster and keep responders safe.
In the United States, NOAA reported 27 billion-dollar weather and climate disasters in 2024. These events caused USD 182.7 billion in damage. Moreover, NOAA data show the 2020–2024 yearly average reached USD 149.3 billion, about 50% above the 2010s. This rising cost pushes agencies toward smart response tools.
Furthermore, public funding and robot sales support market growth. According to FEMA, the agency received USD 29 billion under the American Relief Act, 2025. According to IFR, search, rescue, and security robot sales rose 19% to 3,100 units in 2024. These figures show buyers moving from trials to wider fleet use.
Key Takeaways
- The AI-Powered Rescue Robot Market was worth USD 35.9 billion in 2025 and should reach USD 146.5 billion by 2035, growing at a 15.1% CAGR.
- Land Rescue Robots led with a 65.1% share because ground rescue work is so common.
- Fully Autonomous robots held a 61.1% share, as teams need faster and safer responses.
- AI-Based Navigation and SLAM held 37.2%, showing demand for self-guided mapping.
- Search, Rescue and Disaster Response led applications with a 37.1% share.
- Wheeled/Tracked Ground Platforms captured 55.9% because they move well over rough ground.
- Government and Emergency Response Agencies led end users with a 45.3% share.
- North America led with a 41.2% share and USD 14.8 billion in revenue.
➤ Explore the Premium Report Sample with Full Table of Contents & Insights – https://market.us/report/ai-powered-rescue-robot-market/request-sample/
Market Segmentation
By Robot Type
Land Rescue Robots led the robot type segment in 2025 with a 65.1% share. These ground units work well in collapsed buildings, tunnels, and landslide zones. Moreover, according to USGS, the world recorded 14,132 earthquakes above magnitude 4.0 in 2024. Consequently, rescue teams need sturdy land robots, while aerial robots hold 22.8% and marine robots hold 12.1%.
By Autonomy Level
Fully Autonomous robots held a 61.1% share in 2025, while semi-autonomous models took 38.9%. Rescue teams want faster decisions in risky areas. According to NFPA, U.S. firefighters suffered 53,575 line-of-duty injuries in 2024. Therefore, agencies choose self-guided robots that map rubble and detect gas with little human exposure.
By Technology
AI-Based Navigation and SLAM led the technology segment with a 37.2% share in 2025. Robots need this tool to move through GPS-denied tunnels, mines, and damaged buildings. Moreover, according to DARPA, its USD 82 million SubT Challenge funded underground mapping research. Meanwhile, machine learning at 20.1% and sensor fusion at 15.6% follow behind.
By Application
Search, Rescue and Disaster Response held a 37.1% share in 2025, leading all application areas. According to IDMC, disasters caused 45.8 million internal displacements in 2024, a record high. This scale shows how many people need fast help. Additionally, firefighting holds 18.0%, while military and defense rescue holds 14.8%.
By Mobility
Wheeled and tracked ground platforms captured 55.9% of the market in 2025. These platforms offer stable movement and strong carrying power on rubble and flooded streets. Moreover, according to the U.S. Army, it spent USD 22 million in 2024 to buy and test eight ground vehicles. Consequently, rugged platforms stay ahead of flying, legged, and underwater options.
By End User
Government and Emergency Response Agencies led end-user demand with a 45.3% share in 2025. These agencies hold the budgets, staff, and legal duty to manage disasters. According to the U.S. Fire Administration, 27,166 fire departments were registered by January 2024. Therefore, this large buyer base supports steady robot purchases, while military and defense hold 22.3%.
Regional Analysis
North America held a 41.2% share in 2025 and earned about USD 14.79 billion. According to the U.S. Department of Defense, it set aside around USD 25.2 billion for AI and autonomous systems in FY2025. Consequently, strong defense research and federal disaster agencies give the region a solid base for rescue robot growth.
Asia Pacific grew fastest and held a 26.0% share in 2025. According to the Asian Development Bank, its member countries had 73% of people affected by disasters from 2005 to 2024. Moreover, IFR reports that Asia deployed about 74% of new robots in 2024. Therefore, high disaster risk and strong factories speed up adoption in the region.
Drivers
Rising disaster-response budgets drive steady market demand. According to FEMA, its Disaster Relief Fund provided about USD 29 billion in fiscal year 2025. Consequently, agencies are moving from single robot purchases toward long-term fleet contracts. These contracts also create repeat revenue from software and maintenance.
Additionally, autonomous navigation is maturing in hazard zones. Robots now map collapsed structures and find routes without GPS signals. According to IFR, professional service robot sales grew 9% in 2024 to nearly 199,000 units. Therefore, rescue agencies are gaining more trust in proven self-guided machines.
Use Cases
Urban search teams use AI rescue robots inside collapsed buildings after earthquakes. These robots crawl through rubble, scan for heat signals, and locate trapped survivors. Moreover, they send live maps to the human crews outside. Consequently, rescuers plan safer entry routes and reach victims faster.
Fire departments deploy ground robots during large industrial fires and chemical leaks. These machines carry hoses, measure toxic gases, and stream video from danger zones. Additionally, drones help crews view the full fire scene from above. Therefore, firefighters reduce their direct exposure while still controlling the emergency.
Business Opportunities
Robotics-as-a-Service offers a strong growth path for rescue robot makers. Vendors can bundle hardware with software updates, analytics, and predictive maintenance. Moreover, subscription plans lower upfront costs for smaller fire departments. Consequently, many budget-limited agencies can finally adopt advanced rescue tools.
Additionally, underwater and maritime rescue remains an open space. Coastal nations in Asia Pacific and Europe face floods, ship accidents, and offshore emergencies. Marine robots can search murky waters where divers face high risk. Therefore, companies that build reliable underwater systems can capture new demand.
Major Challenges
Manufacturers face a shortage of engineers skilled in mapping, sensor fusion, and machine learning. This talent gap slows product development and delays government programs. However, companies must spend more on training and university partnerships. Consequently, less money flows into new product design and testing.
Additionally, critical mineral export controls raise supply risks. China controls most of the rare-earth processing used in robot motors and sensors. Licensing rules have cut magnet supplies and pushed material prices higher. Therefore, robot makers face higher costs and longer delays while they qualify new suppliers.
Top Key Players in the Market
- Teledyne FLIR
- Boston Dynamics
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- Shark Robotics
- DEEP Robotics
- Howe & Howe Technologies
- Kongsberg Maritime
- Hydronalix
- Thales Group
- Roboteam
Conclusion
The AI-powered rescue robot market shows strong long-term promise as disasters grow more frequent and costly. Land robots, fully autonomous systems, and smart navigation lead current demand. Moreover, government agencies remain the largest buyers, while North America leads and Asia Pacific grows fastest. However, mineral supply limits and talent gaps need attention. Consequently, subscription models and marine solutions will shape the next growth phase.
Discuss your needs with our analyst
Please share your requirements with more details so our analyst can check if they can solve your problem(s)